
United States Dollar Index holds gains slightly above 101 amid strong US growth prospects
- The US Dollar Index clings to near above 101.00 as strong US PMI figures back Fed’s higher-for-longer interest rates narrative.
- US PMI report for September showed robust manufacturing and service sector activity.
- Oil prices regain ground as Iran vows not to surrender against the US.
The US Dollar (USD) holds onto Wednesday’s strong gains in the Asian trade on Thursday. As of writing, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades firmly near a fresh eight week high of 101.23 posted the previous day.
US Dollar Price This week
The table below shows the percentage change of US Dollar (USD) against listed major currencies this week. US Dollar was the strongest against the Australian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.91% | 1.13% | 0.71% | 0.80% | 1.17% | 0.82% | 0.20% | |
| EUR | -0.91% | 0.24% | -0.18% | -0.11% | 0.26% | -0.08% | -0.69% | |
| GBP | -1.13% | -0.24% | -0.52% | -0.35% | 0.02% | -0.32% | -0.93% | |
| JPY | -0.71% | 0.18% | 0.52% | 0.12% | 0.44% | 0.11% | -0.49% | |
| CAD | -0.80% | 0.11% | 0.35% | -0.12% | 0.43% | 0.00% | -0.58% | |
| AUD | -1.17% | -0.26% | -0.02% | -0.44% | -0.43% | -0.34% | -1.02% | |
| NZD | -0.82% | 0.08% | 0.32% | -0.11% | -0.00% | 0.34% | -0.61% | |
| CHF | -0.20% | 0.69% | 0.93% | 0.49% | 0.58% | 1.02% | 0.61% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
The Greenback gained significantly the previous day due to a sharp recovery in oil prices and the release of the stronger-than-expected United States (US) flash S&P Global Purchasing Managers’ Index (PMI) data for September.
Oil prices recovered sharply on Wednesday Iranian President Masoud Pezeshkian vowed the Islamic Republic will not surrender to the US, in a speech at United Nations (US) General Assembly.
Meanwhile, the US private sector PMI report showed that the overall business activity remained robust due to further growth in both manufacturing and the services sector output.
“US business continues to boom, with output growing at the fastest rate for over five years in September. Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole,” Chris Williamson, Chief Business Economist at S&PGlobal Market Intelligence said.
Signs of a rebound in oil prices after declining for over a weak and strong US economic growth prompt fears of persistent inflation risks, a scenario that strengthens Federal Reserve’s (Fed) higher-for-longer interest rates narrative.
Latest remarks from Fed policymakers have signaled that not only higher energy prices, strong demand is also fuelling inflationary pressures.
US Dollar Index Technical Analysis
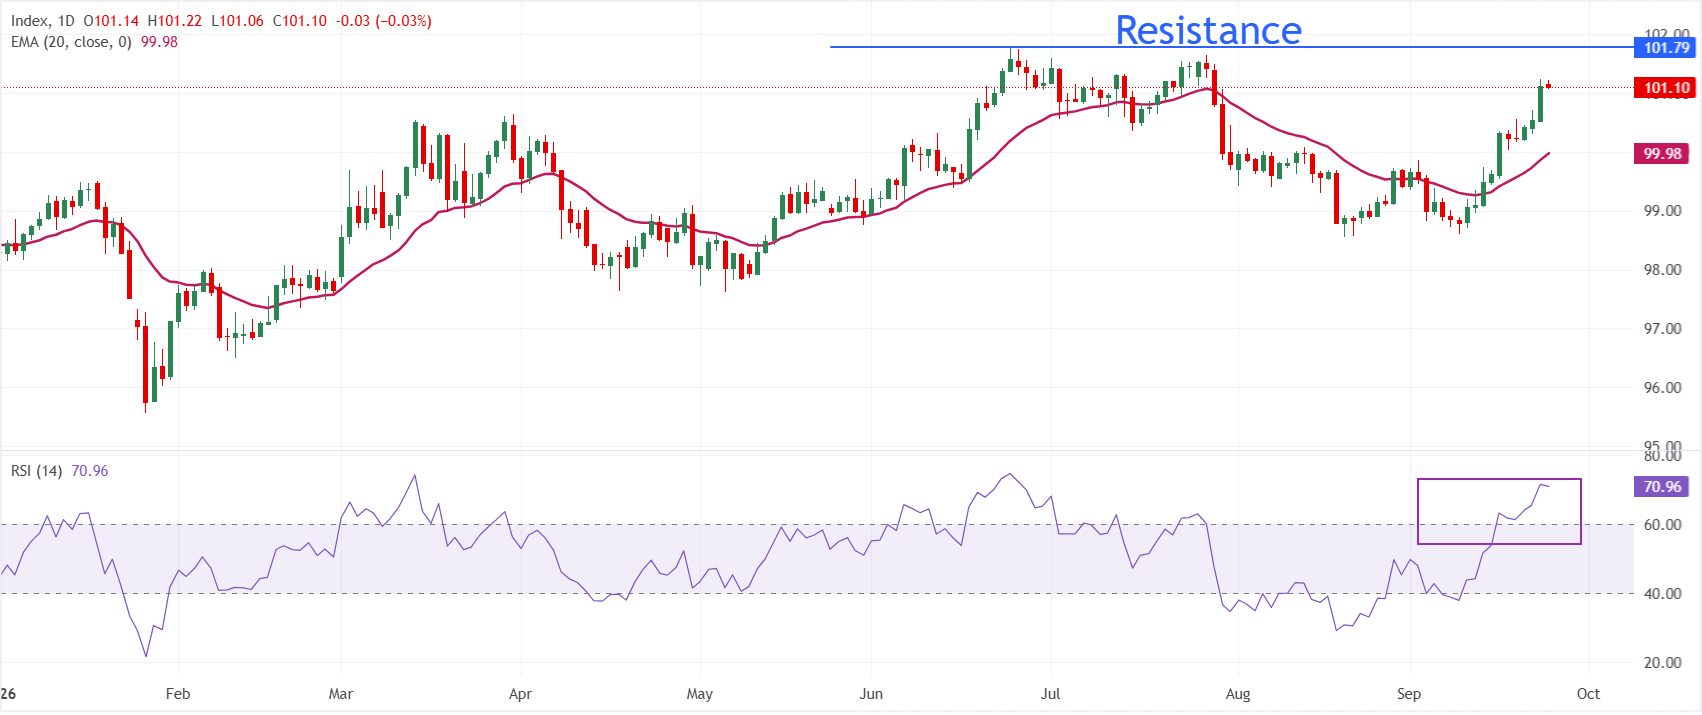
In the daily chart, Dollar Index Spot trades at 101.10, extending its recovery above the 20-period exponential moving average (EMA) at 99.98, which now acts as underlying trend support and keeps the near-term bias bullish. However, the Relative Strength Index (14) at 71.01 sits in overbought territory, suggesting the upside is becoming stretched and raising the risk of a corrective pause or consolidation after the latest push higher.
On the downside, initial support is located at the 20-day EMA around 99.98, where a pullback could find buyers to defend the broader constructive tone as long as price holds above this level. A daily close below 99.98 would undermine the current bullish bias and hint at a deeper retracement, while sustained trade above the EMA keeps scope open for further gains once overbought pressures on the RSI start to unwind.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


