
Why Did South Korea’s KOSPI Index Plunge? 5 Reasons for the Over 16% Drop Over the Past Month and Future Trend Analysis
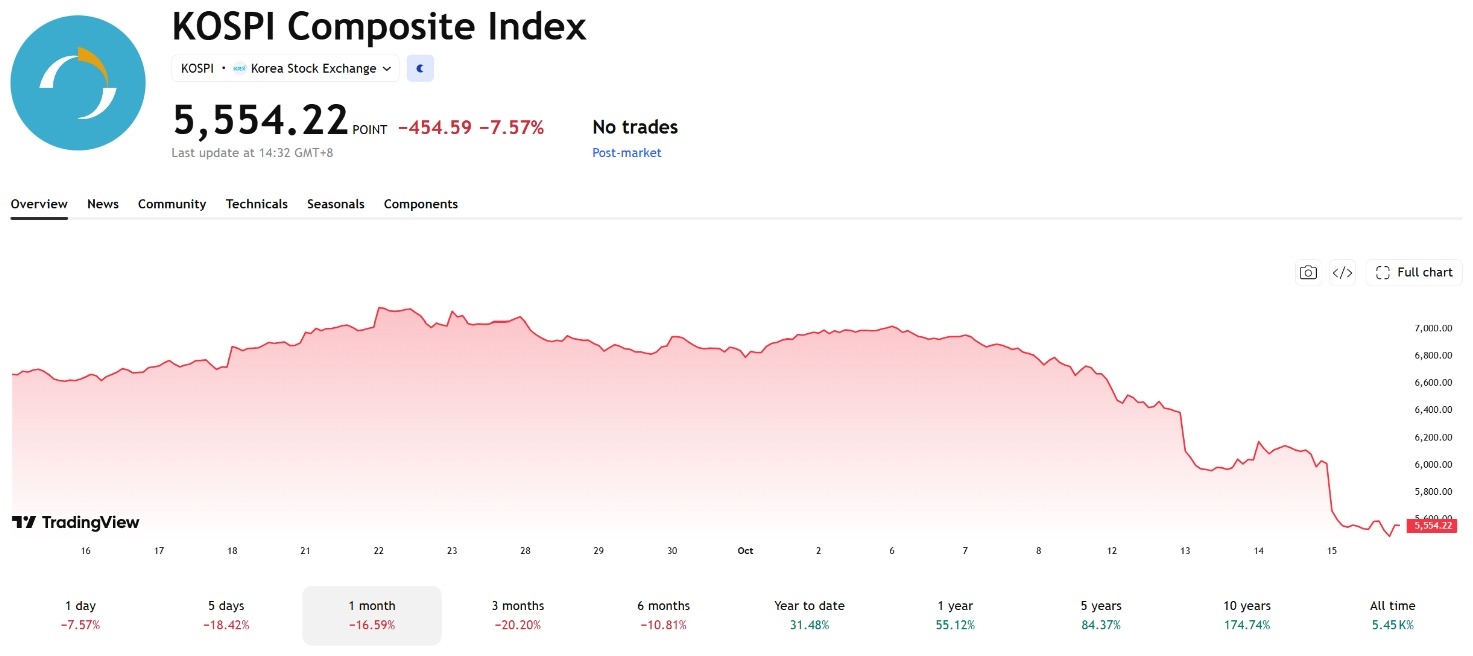
TradingKey - The Korea Composite Stock Price Index (KOSPI) has declined for several consecutive trading sessions. As of the close on October 15, the KOSPI index fell to 5,554.22 points, accumulating a loss of over 16% over the past month. SK Hynix fell more than 10% on the day, while Samsung Electronics dropped over 9%.
[Source: TradingView]
Why Did the Kospi Index Plunge?
South Korean equities have a high reliance on the semiconductor industry, with Samsung Electronics and SK Hynix once having a combined weight of over 50% in the KOSPI Index. When global tech stocks and semiconductor sectors pull back, the KOSPI Index is typically more vulnerable to a drag. Below are five key reasons for this round of decline:
Weakness in U.S. AI and semiconductor stocks. Overnight, the Nasdaq Index fell by about 1.9%, with major AI and semiconductor stocks such as Nvidia, Broadcom, and AMD generally pulling back. The decline in overseas tech stocks created a clear drag on South Korean equities.
U.S. inflation drives up interest rate expectations. The U.S. Consumer Price Index (CPI) rose 3.7% year-over-year in September, higher than August's 3.4% and market expectations. As inflation pressures mounted, the market reassessed the Federal Reserve's policy trajectory, stoking expectations of rate hikes and putting greater valuation pressure on high-valuation tech stocks.
Scrutiny over returns on AI capital expenditures. Big tech companies continue to expand investments in AI data centers, but the market has begun to reassess whether these outlays can translate into stable revenue and profit. If the commercialization of AI applications falls short of expectations, valuations of chipmakers and data center companies could come under pressure.
CXMT's technological progress raises DRAM competition expectations. CXMT recently disclosed technical advancements in 4F² DRAM and plans to push forward server DDR5 products. Currently, its mass-production scale, product yield, and customer qualifications remain unclear. If it achieves mass production and expands supply in the future, traditional DRAM prices and memory makers' profit margins could be affected.
Uncertainty surrounds the pace of HBM4 capacity expansion. According to South Korean media reports, some of SK Hynix's HBM4 back-end equipment originally scheduled for deployment in the second half of this year may be delayed until next year, raising market concerns over the company's expansion speed and short-term earnings expectations. Currently, there is no evidence indicating substantive issues with SK Hynix's HBM4 mass production.
Kospi Index Outlook
The 6,000-point mark is a key psychological level watched by the market. If the KOSPI remains below this level, selling pressure may persist; if it reclaims 6,000 points, market sentiment could gradually improve.
The medium-term trajectory depends on the Federal Reserve's interest rate policy, global AI capital expenditures, HBM orders, DRAM prices, and South Korean corporate earnings.
If AI server investment continues to grow, HBM orders remain strong, and DRAM prices stay elevated, earnings at Samsung Electronics and SK Hynix will remain supported. However, if AI capital expenditures slow down, ChangXin Memory Technologies accelerates mass production, or DRAM prices weaken, the KOSPI may remain highly volatile.
Is Now the Time to Buy?
After the KOSPI fell below 6,000 points, valuation pressures on certain semiconductor stocks eased somewhat, but market risks have not vanished. If AI demand and memory prices remain strong, the current pullback may offer long-term investors opportunities to build positions in stages; however, if rate hike expectations heat up, foreign capital continues to flow out, or ChangXin Memory Technologies' mass production progresses faster than expected, related stocks could still undergo further correction.
Therefore, at this stage, it is inadvisable to judge buying opportunities solely based on sharp index declines; it is more suitable to observe and build positions in tranches. Investors should focus on whether the KOSPI can reclaim 6,000 points, whether Samsung Electronics and SK Hynix can stem their declines, and whether HBM4 shipments, DRAM prices, and earnings expectations improve.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


