
Qualcomm Stock Price Forecast: Plunges to Two-Month Low Post-Earnings, Could Drop Over 20% More
TradingKey - Qualcomm earnings pressuring revenue hits bulls as stock plunges to a nearly two-month low; technical breakdown poses risk of further 20% decline.
After U.S. market close on November 4 ET, Qualcomm Incorporated (QCOM) reported its fiscal 2026 fourth-quarter (Q4) financial results. Although adjusted revenue and EPS slightly beat Wall Street expectations, core smartphone chip revenue plummeted 26% in a single quarter. Combined with management's gross margin warning over surging foundry and memory costs, QCOM stock tumbled nearly 9% after hours, breaching the $160 mark to hit a nearly two-month low. Currently, the market is on high alert over whether Qualcomm will repeat a semiconductor cyclical valuation derating, dropping further to test support at $120.
Although Qualcomm's automotive and IoT revenues combined grew 36%, it was still unable to fill the massive gap left by the contraction in smartphone revenue. According to financial data, Qualcomm's Q4 chip business (QCT) revenue fell 8% year-over-year to $9.015 billion, with handset chip revenue—the largest component—plummeting 26% to $5.137 billion.
In addition, surging upstream supply chain costs put Qualcomm's gross margin under pressure. Management candidly stated that input costs across foundry services, packaging and testing, advanced packaging, and memory have generally risen. Although Qualcomm is adjusting product pricing, the full pass-through benefit will not be reflected in gross margin until the second half of fiscal 2027, meaning the company will face a period of margin compression over the next 2 to 3 quarters.
Even more damaging, the Democratic Party achieved a major victory in the U.S. midterm elections, regaining control of both the Senate and the House of Representatives. Against the backdrop of Democrats controlling the U.S. Congress, market concerns over CHIPS Act add-on clauses, antitrust regulation, and international trade policy are rising, threatening to keep Qualcomm's stock under continued pressure.
From a technical and market structure perspective, after breaking below its 50-day moving average, Qualcomm's stock price faces a key gap-fill and a battle to defend the 200-day moving average. The corresponding price level of $148.00–$150.00 brings together the long-term 200-day dynamic moving average and serves as a strong bottom turnover zone from mid-2026. If QCOM can demonstrate strong spot buy-the-dip support at this level, the stock will have an opportunity to maintain a high-level box range above 150, preventing further deterioration.
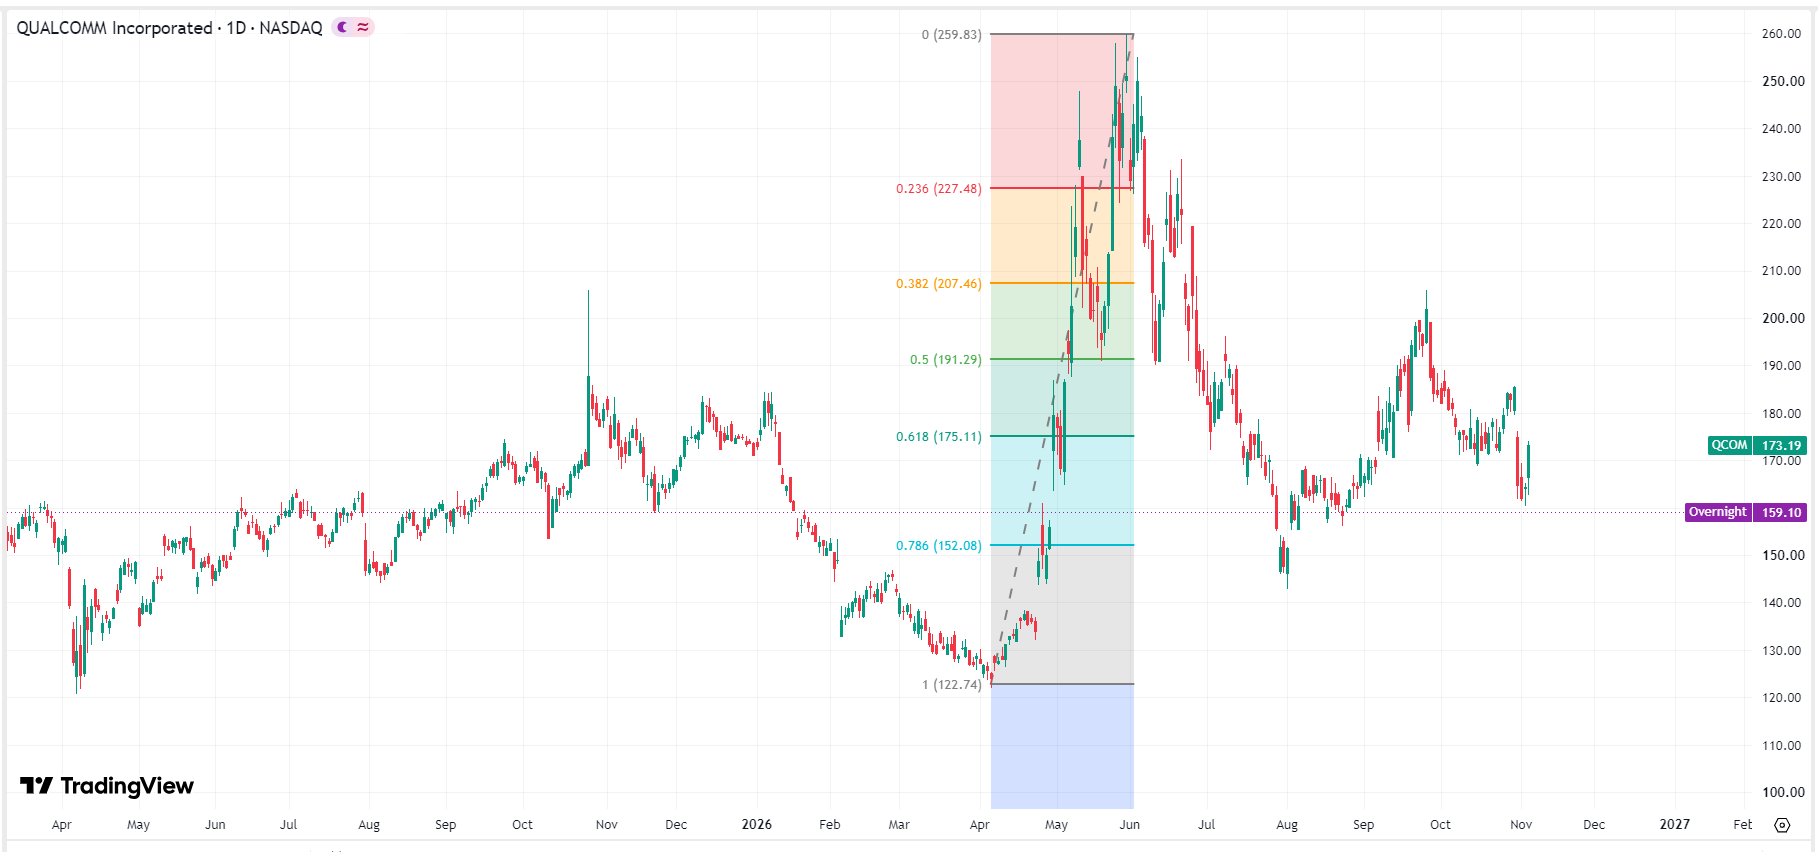 Qualcomm stock price chart, Source: TradingView
If post-election risk-averse sentiment in the broader U.S. stock market remains elevated, pushing Qualcomm's stock below the key support line of $148, technicals will confirm a head-and-shoulders breakdown. Following a 1:1 measured downward move, the stock would face a secondary drop of approximately 24%, aiming directly for $120, where the forward P/E ratio would pull back to a historical valuation bottom of 12x.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


