
Today’s Market Recap: Chip Stocks Rebound as Micron Rises Over 5%, AMD Gains Over 6%, Intel Jumps Nearly 8%
Tracking Market Trends
TradingKey - On September 17 Eastern Time, the three major US stock indices bounced back across the board, snapping a three-day losing streak. International oil prices fell for a second consecutive day, while the 10-year US Treasury yield slipped back below 5%, easing the pressure on US equity valuations caused by the simultaneous rise in energy prices and long-term interest rates. Meanwhile, US initial jobless claims dropped to 196,000, indicating that the labor market remains resilient. Tech and semiconductor stocks led the gains, with the Nasdaq advancing nearly 1.7%.
At the close, the Dow Jones Industrial Average rose 0.61% to 51,783.17; the S&P 500 gained 1.14% to 7,637.76; and the Nasdaq Composite Index surged 1.69% to 26,418.30.
In terms of sectors and individual stocks, semiconductor stocks rebounded noticeably. Intel (INTC) rose 7.67%, AMD (AMD) gained 6.36%, Micron Technology (MU) climbed 5.5%, Nvidia (NVDA) advanced 2.54%, Broadcom (AVGO) rose 2.29%. The chip sector, which had sharply corrected earlier after AI industry executives called for slowing down model development, saw a clear recovery.
In commodities, international oil prices fell for a second straight day but remained above $100. Brent crude (UKOIL) fell 1.43% to settle at $104.1; WTI crude (USOIL) dropped 0.91% to settle at $101.1. Market concerns over supply disruptions were partially eased as Saudi Arabia increased crude supply through Oman's Sohar port and sought to restore about half of the capacity of its East-West pipeline within days. However, as the conflict between Saudi Arabia and Yemen's Houthi rebels continues, the risk premium on oil prices has not entirely vanished.
In precious metals, gold (XAUUSD) rebounded sharply. Spot gold rose 1.82% to $4,341.59. The pullbacks in oil prices and US Treasury yields, along with a weakening US dollar off near seven-week highs, provided support for gold prices.
In cryptocurrencies, Bitcoin (BTCUSD) climbed back to near $76,600, up 0.28%. Although the Fed's latest dot plot still hinted at a potential additional rate hike within the year, the market viewed this week's 25-basis-point rate hike as having been largely priced in, while the SEC's new policy on tokenized securities improved crypto market sentiment.
Market News
Goldman Sachs expects the Fed to raise interest rates by another 25 basis points in October. Following the Fed's policy rate hike to 3.75%–4.00% this week, Goldman Sachs revised its previous forecast to expect a second consecutive 25-basis-point rate hike at the October meeting. The Fed's latest projections show that 16 of the 18 officials submitting interest rate forecasts expect at least one more rate hike this year, with four expecting two more hikes. Current market pricing indicates an approximately 53% chance of a rate hike in October and an approximately 81% chance of another hike in December.
The U.S. SEC introduces a five-year exemption framework for tokenized stock trading. The SEC allows qualifying platforms to trade blockchain tokens representing real company shares, granting partial regulatory exemptions to trading platforms and liquidity providers. The new rules require tokenized stocks to offer the same dividend and voting rights as traditional shares, while banning "synthetic stock tokens" that merely track share prices without representing actual ownership. Companies such as Coinbase and Robinhood have previously expressed plans to enter the U.S. tokenized stock market.
U.S. initial jobless claims fall to 196,000 as the labor market remains resilient. According to U.S. Department of Labor data, initial claims for unemployment benefits fell by 10,000 to 196,000 last week. Meanwhile, single-family housing starts rose 7.6% month-over-month in August, but building permits fell 1.8%, reflecting ongoing pressure on the housing market from high interest rates. The average rate on a 30-year fixed mortgage in the U.S. has risen to 6.95%, the highest level since January 2025.
Saudi Arabia increases crude exports via Oman; global oil prices fall for a second consecutive day. Saudi Arabia is boosting supplies to Asian refiners via ship-to-ship transfers at Oman's Port of Sohar to make up for export losses caused by attacks on the East-West Pipeline and the Port of Yanbu. Reports also indicate that three pumping stations on the attacked pipeline were damaged, but Saudi Arabia is working to restore about half of its transport capacity in the coming days.
CoreWeave plans to issue $3 billion in convertible bonds. Nvidia-backed AI cloud computing company CoreWeave announced a $3 billion convertible bond offering to support its AI infrastructure expansion. The company has rapidly scaled up investments in data centers, GPUs, and computing power, and this latest fundraising underscores the massive capital requirements for expanding AI infrastructure. The company's stock closed down 4.2% on the day.
Amazon joins the AI safety debate, but does not support a broad slowdown in AI development. Amazon (AMZN) stated that AI models should be released only after rigorous testing and establishing adequate safety measures, while emphasizing that "technological progress and safety are not mutually exclusive." This stance differs somewhat from recent public discussions by companies like OpenAI and Anthropic regarding advanced AI risks, with AI safety and regulation remaining key issues for the tech industry.
Huawei says China's demand for AI chips exceeds current supply capacity. Eric Xu, Huawei's rotating chairman, stated that the company's current production capacity for AI computing equipment remains insufficient to meet domestic demand in China, so it has no plans for a large-scale overseas expansion for now. Huawei also plans to accelerate the rollout of its next-generation Ascend 960 series AI chips and continue expanding its AI computing systems to compete with Nvidia in China's AI computing market.
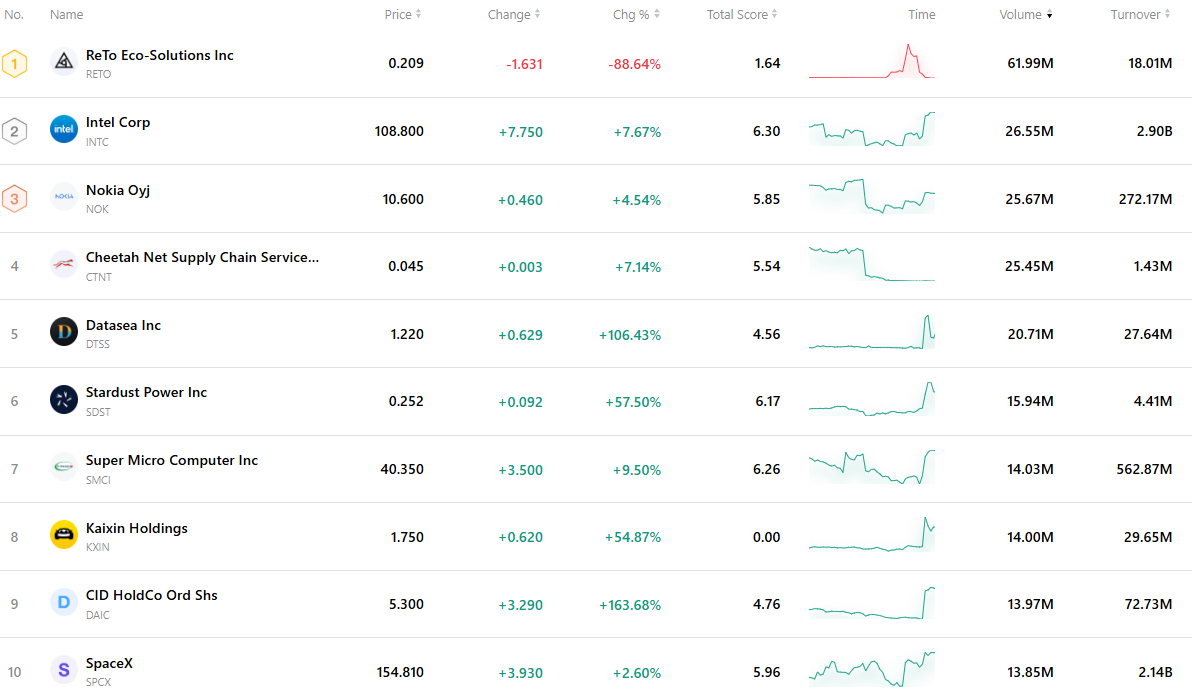
Top 10 Most Active Stocks
The table below lists the ten most actively traded stocks in the latest market session. Supported by massive trading volumes and robust liquidity, these assets have become key benchmarks for tracking global market dynamics.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


