
Microsoft Stock Price Forecast: Redburn Raises Price Target to $440, Will AI Investment Controversy Drag Down MSFT?
TradingKey - Rothschild & Co Redburn, after updating its valuation model, raised Microsoft's (MSFT) price target from $400 to $440, while continuing to maintain its "Neutral" rating.
The price target increase stems primarily from a valuation recovery in the Software-as-a-Service (SaaS) sector, rather than Redburn significantly raising its earnings growth expectations for Microsoft. The higher price target alongside an unchanged rating reflects the firm's recognition of Microsoft's competitiveness in cloud computing and enterprise software, while suggesting that the current valuation already prices in much of the growth potential from its AI business.
AI Business Continues to Expand as Capital Returns Become Core to Valuation
Microsoft's primary growth driver remains Azure, Copilot, and its OpenAI-related artificial intelligence business. Growing enterprise demand for AI inference, data analytics, and intelligent agents is bringing more cloud computing workloads to Azure, while also helping Microsoft embed AI capabilities into Office, GitHub, and security products.
However, as Microsoft continues to expand investments in data centers, chips, power, and cooling facilities, the market is turning its attention to how long it will take to recoup these costs.
Investor Michael Burry recently pointed out that data centers often take several years from planning to completion, accompanied by long-term power, land, and lease commitments, whereas the refresh cycle for AI hardware such as GPUs may only be two to three years. If next-generation chips adopt different power supply, thermal, and rack designs, some highly customized infrastructure could face risks of lower utilization or premature modification.
This view does not mean Microsoft's AI strategy is bound to fail, but it underscores the importance of return on capital, depreciation cycles, and free cash flow. If Azure AI revenue and paying Copilot users continue to grow, the current high level of investment will build a deeper moat of scale. Conversely, if computing power utilization and commercialization progress lag behind expectations, depreciation and operating costs could exert sustained pressure on profit margins.
Therefore, over the next few quarters, Microsoft not only needs to maintain cloud growth, but also must demonstrate that incremental AI revenue is sufficient to cover rapidly rising capital expenditures.
Safety and Copyright Risks Will Not Stop AI Expansion
In addition to capital returns, safety and regulation are also key variables affecting Microsoft's AI valuation. Mustafa Suleyman, head of Microsoft's AI business, recently stated that international competition should not be used as a reason to abandon necessary safety guardrails, and advanced AI systems should always remain under human control and be subject to explicit risk assessments and industry standards.
However, Microsoft's stance is not to slow down AI R&D, but rather to strengthen oversight while expanding commercial applications. For enterprise and government customers, data protection, identity management, and system reliability are themselves crucial criteria when choosing an AI platform. If Microsoft can fully integrate safety capabilities into Azure and Copilot, such investments could instead increase customer stickiness and solidify its lead in the enterprise AI market.
Copyright litigation introduces another layer of uncertainty. The New York Times accused Microsoft and OpenAI of using copyrighted content to train models without permission, alleging that some generated outputs could replace original reporting.
The U.S. Department of Justice recently filed a "statement of interest," asserting that AI model training is highly transformative and warning that a comprehensive training data licensing regime could raise industry entry barriers. While this stance is generally favorable to Microsoft and OpenAI, it is not equivalent to a court ruling.
Reports indicate that the Department of Justice did not fully coordinate with the U.S. Patent and Trademark Office and the Copyright Office prior to submitting the filing, highlighting ongoing disagreements within the U.S. government over AI copyright policy. If courts ultimately require AI firms to pay higher data licensing fees, both Microsoft's model training costs and legal liabilities could rise.
Microsoft Stock Price Technical Analysis
Source: TradingView
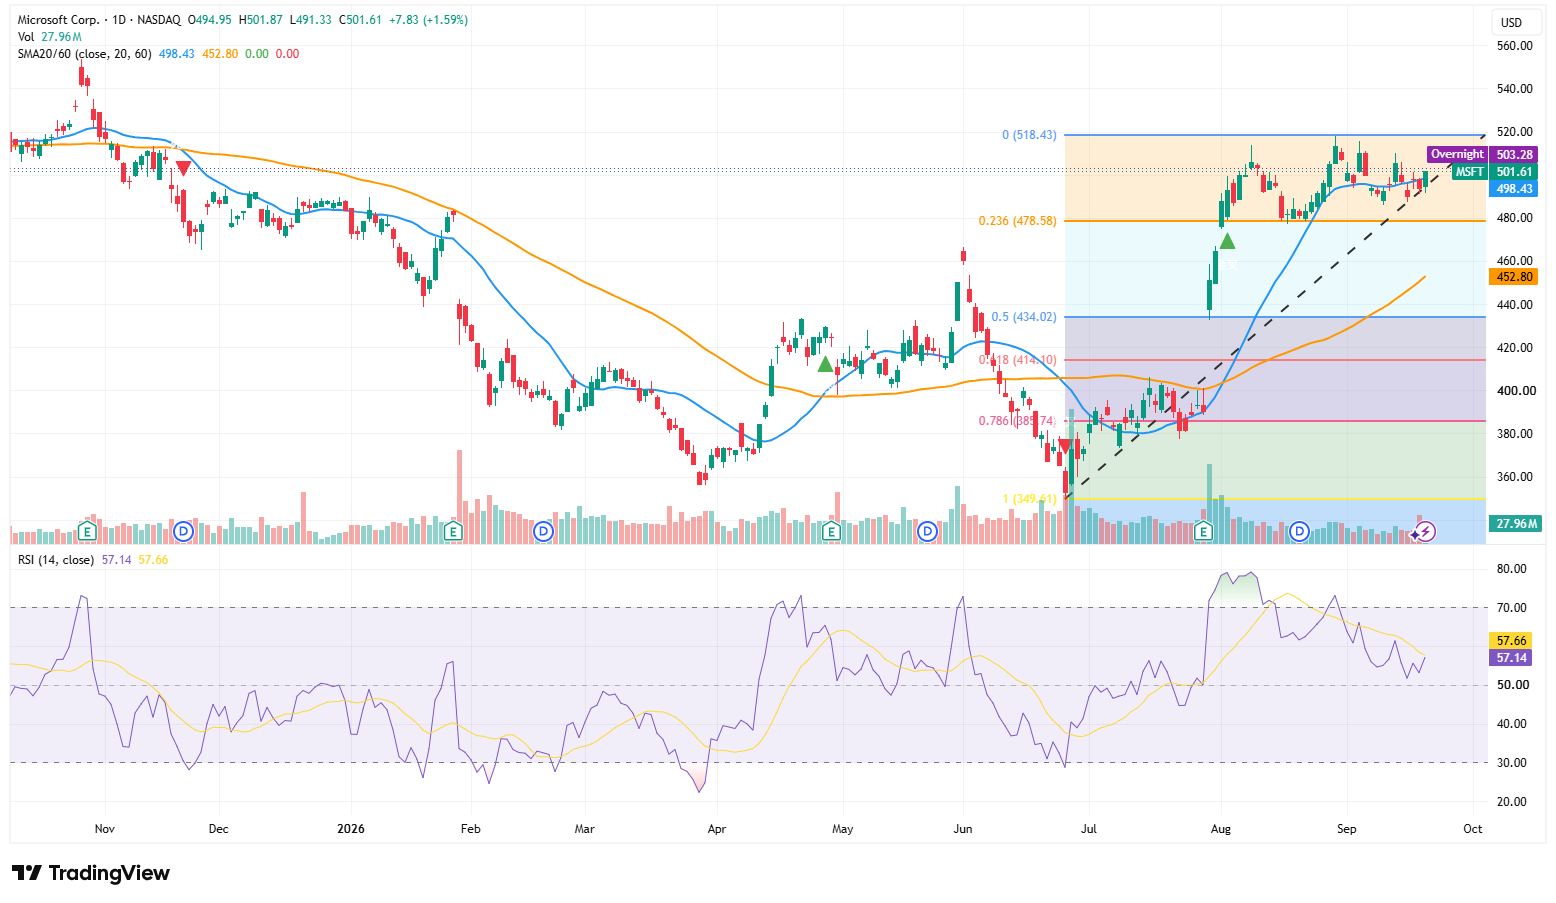
Microsoft stock closed at $501.61 on the 21st, reclaiming its 20-day moving average of $498.43. With the 20-day moving average remaining above the 60-day moving average of $452.80, the medium-term trend stays bullish. The stock price is currently consolidating mainly in the $478.58–$518.43 range, and the uptrend line remains intact.
Primary support lies at $490–$498, followed by the 0.236 retracement level at $478.58. If the daily chart falls below this level, it may further retest around $454 and $434.02. Upside resistance is concentrated at $503–$510 and the previous high of $518.43. A high-volume breakout above the previous high could bring extension targets of $540 and around $564 into focus.
The RSI stands at 57.14, remaining in neutral-to-bullish territory but slightly below the signal line, indicating that short-term momentum has not yet shown a clear acceleration. Therefore, while AI investment controversies may increase volatility, they have not yet altered the medium-term uptrend structure.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


