
Vail Resorts Stock Forecast: Can MTN Earnings Reverse Its 2026 Slump?
TradingKey - Vail Resorts (MTN) is releasing Q4 and full-year fiscal 2026 results on Monday, September 28, after the market closes. With that in mind, traders should keep in mind Monday’s regular-session closing price will not reflect results released after the close. That said, Monday’s report should give some insight into the company’s preliminary thoughts on the ski season and Epic Pass sales. Below are our thoughts on the reports.
Poor Snowfall Drove a Major Earnings Reset
In Q3, Vail Resorts reported a large decline in results, due to the lack of snow in the West. Overall, resort revenue decreased by 7.0%, and Resort Reported EBITDA declined by 9.5%, to $586.4 million. Skier visits declined by approximately 15%, with the Rockies and Tahoe regions, experiencing the largest declines. Lift revenue declined by 5.0% and was offset by passes sales, which occur in prior periods. Pass sales, do provide some protection to resorts, but the main concern is visitors and guest spending.
In an effort to anticipate the guests' spending, and overall visits for the year, Vail Resorts first lowered its fiscal 2026 guidance on March 9 and then reduced it again on June 8, to a range of $735 million to $755 million for Resort Reported EBITDA and $128 million to $162 million for net income. At the mid-point, the guidance represents a 14.0% decline from the originally fiscal year guidance. The completed fiscal year has not yet been reported; Monday’s release will show where results landed within or relative to the updated range. Therefore, the reports Monday should provide more color on the year.
Epic Pass Sales Are the Bigger Earnings Catalyst
There is more significance in the upcoming ski season than the recent quarter’s results. Through May 26, Vail Resorts’ North American pass product unit sales for the 2026/27 season reported a 10% decrease compared to the same period last year. Estimated ski days sold and pass sales dollars also decreased by 8% and 5% respectively. Management stated that the lack of natural snow in the Western United States last season negatively impacted pass sales. Pass demand was also negatively impacted by the fact that some customers decided to postpone their purchase.
Management expects an opportunity for pass performance to improve during the fall selling season as some delayed customers return. Monday will determine how well Management’s expectations are developing. If ski pass sales dollars increased, customers may have decided to purchase pass products this season after all. If ski pass sales and dollars continue to decrease, customers may have decided not to purchase season passes due to last season’s low natural snow. I believe the latest update on season ski passes is more important than last quarter’s results.
Australia Offers a More Encouraging Signal
There were some positive signs in the pass data outside North America.
The Epic Australia Pass reported a 26% increase in pass sales and a 31% increase in sales dollars through the end of May.
Positive data like this should help Vail Resorts during their upcoming earnings release.
There is a good chance that the Australian ski season aided Vail Resorts during the fourth quarter, and it should be factored into the company's earnings and guidance for the following year.
A Seasonal Q4 Loss Would Be Normal
I would look for evidence that supports a loss for fiscal Q4 2026 in the range of -$5.29 per share and revenue in the range of about $272 million.
While Vail Resorts lost money and reported low revenue in last year’s fiscal fourth quarter, approximately $271.3 million in revenue and a loss per share of $5.08 do provide a slight frame of reference for what to expect.
Other factors will be more important this time around. These will likely be the impact of Vail Resorts’ cost cutting and restructuring efforts, the positive or negative impact of the Australian operations, and management’s forward looking statements on the upcoming U.S. Ski season.
Cost Savings Could Provide an Important Offset
Vail projects $106 million in annual cost savings from its operational improvements. About $13 million of one-time transformation costs were included in the revised fiscal 2026 Resort EBITDA guidance; they are not part of the $106 million annualized savings figure. The report released Monday should provide more information about how those cost savings impacted Vail this fiscal year, and what management expects in FY2027.
Changes in the weather, or cost saving measures, can improve the bottom line. However, positive changes to the bottom line can also be achieved by increasing the number of pass sales and/or the number of visits to the resort. The best case scenario would be improved guest visits and spending while also improving savings and efficiencies.
The Epic Experience Strategy Faces an Early Credibility Test
Management is placing a greater focus on guests and experiences by enhancing and modernizing food and beverage and rental services, as well as improving snow making. The idea is to improve the guest experience and increase repeat visits.
Although management may not be able to disclose all of their plans for the Epic Experience strategy during this quarter's earnings call, they may be able to set more specific goals and provide more clarity. The Epic Experience strategy will be more effectively judged by guest spending and visits in future seasons.
Board Pressure Raises the Execution Stakes
There are a few governance considerations to be aware of as you prepare for earnings. In September, Oasis Management Company nominated four individuals to the Vail board of directors. Vail, however, has said it will consider board changes as part of its refreshment process. Regardless of Vail’s commitment, Board nominations process are typically not completed until after earnings.
That said, nominations process create a heightened sense of urgency on management to communicate a plan to enhance business performance. Therefore, the types of questions management will face in the earnings call about the Company’s performance and guidance will be extensive.
What Would Strengthen the Bull Case
In the near term, I believe it will be prudent to maintain a neutral to bearish outlook on the stock, until Vail releases more current Pass data. As of now, the market is expecting Vail to report normal seasonal loss for the quarter. I will likely increase my equities exposure if the Pass sales data for the year shows a material improvement, North American Pass Sales data shows a material improvement, the Company issues FY27 guidance, and Resort EBITDA for the year was in line with guidance.
On the other hand, if Pass sales data for the year shows no improvement, and Vail continues with its high expenditure initiative, I will likely reduce my exposure to the stock.
Vail Resorts Technical Analysis: MTN Compresses Below $142.77 as Triangle Nears Breakout
Vail Resorts’ last reported close was $140.05. Their 2 hour chart shows price action making a rebound from the recent low near $129.18 and consolidating in a symmetrical triangle.
The current price action showing compression between rising support and a descending trendline is still pertinent and setting up the potentially bearish breakdown of the triangle. Price action is currently compressed between $137.47 and $142.77.
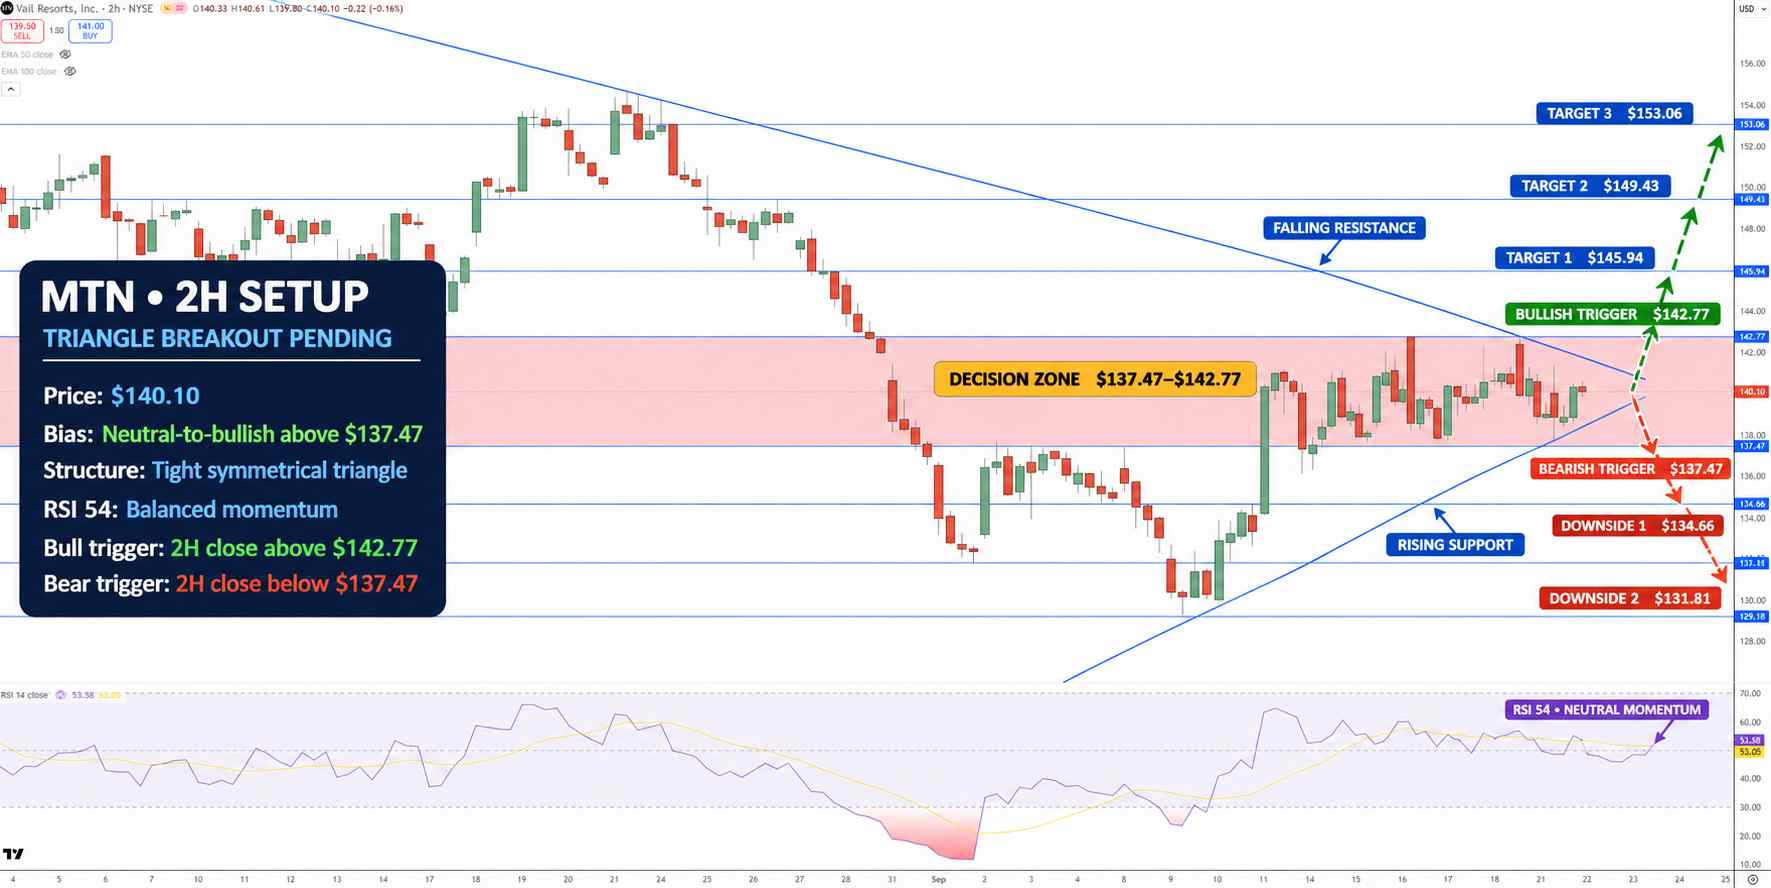
Vail Resorts Stock Price Chart - Source: Tradingview
The RSI of 54 also reflects the compression of the triangle. The descending trendline around $141 to $142 is the immediate resistance zone, while a bearish breakdown would require a move below $137.47.
A break above $142.77 would target $145.94 with additional resistance at $149.43 and $153.06 possible upside targets.
Price action below $137.47 would negate the bullish case and shift focus toward lower support at $134.66, followed by $131.81.
I am neutral to slightly bullish on MTN, but a break below $137.47 would weaken that view and strengthen the bearish case. Earnings reports could cause an atypical gap.
Why is Vail Resorts stock in focus now?
Vail Resorts will release fiscal Q4 and full-year 2026 results on September 28 after the market close. Expectations are low for Q4, but market participants will pay close attention to the latest Epic Pass sales numbers, Resort level EBITDA, operating costs, and forward-looking comments on fiscal 2027.
What level confirms a stronger MTN breakout?
A sustained 2-hour close above $142.77 would signal a breakout from the current triangle pattern and target $145.94. Further gains could be expected up to $149.43. A close below $137.47, however, could negate the pattern and target a move lower.
Bottom Line
Mounting evidence points to challenging conditions for the ski business this season, and Vail Resorts is likely wanting to see more evidence that customer demand is stabilizing.
Expectations are low for Q4 due to seasonal factors. The focus is more on Epic Pass sales, FY2027 outlook, and the potential for costs savings to offset is business operating losses.
The bias on MTN is still neutral-to-bullish with support at $137.47. A break of $142.77 to the upside would bring the target of $145.94 into focus.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


