
【US Pre-Market】Anthropic Valuation Under Pressure, CRWV Drops Over 4%, Tesla Roadster Drives Stock Up Over 4%
TradingKey - US stock index futures were mixed in pre-market trading on Friday (October 16) US Eastern Time. Federal Reserve Chair Kevin Warsh offered no clear signals regarding the October and December interest rate decisions, causing the US Dollar Index to weaken. Meanwhile, concerns over artificial intelligence company valuations and financing costs continued to weigh on tech stocks, as the market awaited economic data such as US industrial production.
As of press time, Dow futures were up 0.06%, S&P 500 futures gained 0.08%, and Nasdaq 100 futures fell 0.23%.
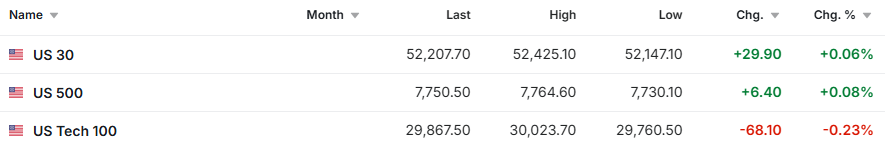
Source: Investing
In commodities, international oil prices pulled back slightly, with WTI (USOIL) crude down about 1.5%, trading near $96, while Brent (UKOIL) crude held near $106.3. Although oil prices pulled back intraday, shipping disruptions in the Strait of Hormuz and Middle East supply risks kept oil prices elevated. Gold (XAUUSD) rose about 0.2% to near $4,180, while the US Dollar Index fell about 0.4% to 101.65, providing support for gold prices.
In cryptocurrencies, Bitcoin (BTC) rose about 0.7%, trading near $82,800. Despite the short-term rebound, Bitcoin remains down about 0.5% over the past seven days.
Market Moves
Tesla (TSLA) rose over 4% in pre-market trading. The company unveiled its next-generation Roadster, demonstrating features such as brief hovering enabled by compressed-air thrusters derived from SpaceX technology. Tesla reopened Roadster reservations with a mass production target set for 2028, with the new model unveil boosting investor expectations for the company's product cycle.
Alcoa (AA) rose about 2.5% in pre-market trading. The company reported third-quarter adjusted earnings per share of $1.82, above the market consensus of $1.47, while revenue stood at $3.704 billion, slightly below the expected $3.785 billion. Free cash flow reached $472 million for the quarter, with management expecting to maintain strong operational performance in the fourth quarter.
CoreWeave (CRWV) fell over 4% in pre-market trading. Market concerns persist regarding the sustainability of the company's debt-financed AI data center expansion, with yields on some of its long-term bonds rising to around 15% and credit default swap costs remaining high. The company's previously announced equity offering and convertible bond financing plans have further heightened dilution fears.
Chip and memory stocks were mostly down in pre-market trading. Micron Technology (MU) fell over 2%, AMD (AMD) dropped about 1.4%, while Nvidia (NVDA) edged up roughly 0.2%. AI infrastructure financing costs and related valuation issues continued to weigh on risk appetite for high-valuation tech stocks.
Market News
Federal Reserve Chair Warsh declined to prejudge interest rate decisions for the remainder of the year. Speaking during the IMF and World Bank Annual Meetings, Warsh stated that the Fed will deliver on its price stability mandate, but will not prejudge the policy outcomes of its October and December meetings, nor did he provide new clues on the timing of the next rate hike.
U.S. September PPI and retail sales both showed strength. Data from the U.S. Bureau of Labor Statistics showed that the September final demand PPI rose 1.3% month-over-month and 6.3% year-over-year, marking the largest monthly gain since March 2022; meanwhile, U.S. Census Bureau data showed that retail sales increased 0.8% month-over-month to $745 billion in September.
Anthropic's potential IPO valuation was reportedly revised downward. Reuters reported, citing people familiar with the matter, that some existing and potential investors discussed valuing Anthropic at around $1.5 trillion, below previous expectations of around $2 trillion. In addition, Anthropic's third-quarter revenue grew 45% quarter-over-quarter to $16.8 billion, achieving adjusted profitability.
The International Energy Agency released additional fuel reserves. The IEA agreed on Thursday to release more than 20 million barrels of diesel into the market, along with the remaining crude oil from its previous emergency reserve release plan. Kpler data showed that for the week ended October 13, crude oil flow through the Strait of Hormuz averaged approximately 11.62 million barrels per day, equivalent to 68% of the normal baseline level.
Key Data and Events Preview
At 8:30 AM ET on October 16, the US released September import and export price indices.
At 9:15 AM ET on October 16, the US released September industrial production and capacity utilization.
At 12:45 PM ET on October 16, the New York Fed released its latest economic Nowcast.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


