
【US Pre-Market】TSMC's Record Profit Fails to Save Chip Stocks as Nvidia, Micron Fall Ahead of US PPI
TradingKey - On Thursday (October 15) Eastern Time, futures on the three major US stock indexes diverged in pre-market trading. AI infrastructure financing risks continued to weigh on tech stocks, while Dow futures rose slightly, driven by capital shifts into traditional blue-chip and defensive sectors. US September CPI released on Wednesday rose 3.7% year-over-year, higher than the market expectation of 3.6%, raising concerns over further rate hikes by the Federal Reserve; investors are also awaiting today's concentrated release of PPI, retail sales, and initial jobless claims data.
As of press time, Dow futures were up 0.27%, S&P 500 futures were down 0.17%, and Nasdaq 100 futures were down 0.99%.
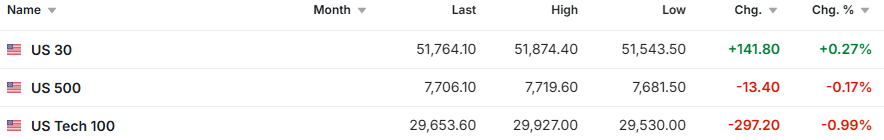
Source: Investing
In commodities, gold (XAUUSD) rose about 1.3% to near $4,160, with a weaker US dollar, rising credit risk in the AI sector, and geopolitical safe-haven demand jointly supporting gold prices. WTI (USOIL) crude oil hovered at high levels around $95.2, as shipping security risks in the Strait of Hormuz limited downside space for oil prices.
In cryptocurrencies, Bitcoin (BTC) fell about 0.7%, trading around $81,200. Rising inflation, rate-hike expectations, and the sell-off in tech stocks combined to dampen demand for high-volatility risk assets.
Market Action
TSMC (TSM) ADR fell about 1.9% in premarket trading. The company's third-quarter revenue reached $46.72 billion, up 41.2% year-over-year; net profit was NT$763.06 billion, up 68.7% year-over-year, setting a profit record for the sixth consecutive quarter. TSMC expects fourth-quarter revenue of $52.3 billion to $54.3 billion, but management remains cautious about the macroeconomic environment in 2027 and warned that overseas capacity expansion will continue to weigh on profit margins, with strong results failing to reverse the stock's decline.
Chip and memory stocks fell across the board in premarket trading. Micron Technology (MU) fell about 4.5%, AMD (AMD) dropped about 3%, and Nvidia (NVDA) fell nearly 2%. A higher-than-expected CPI reignited rate-hike risks, while market concerns that high financing costs could slow the pace of AI data center construction led tech stocks to extend the previous session's sell-off.
Oracle (ORCL) fell about 1.8% in premarket trading, while CoreWeave (CRWV) dropped over 6%. As the market continues to assess the risks of AI infrastructure companies relying on debt-funded expansion, bond prices for Oracle and CoreWeave came under pressure, with related credit default swap costs rising to record highs.
Rocket Lab (RKLB) tumbled over 10% in premarket trading. The company announced that it has delayed the inaugural launch of its Neutron medium-lift launch vehicle to 2027, having previously targeted a maiden flight in the fourth quarter of 2026.
Market News
Credit risk metrics for AI companies have climbed to record highs. Data from S&P Global Market Intelligence showed that Oracle's five-year credit default swap spread stood at 288 basis points, up from 260 basis points a week earlier; CoreWeave's spread broke above 1,000 basis points, with the yield on its bonds maturing in 2032 rising to around 16%.
Anthropic's third-quarter revenue reportedly grew 45% quarter-on-quarter. According to two people who attended the company's pre-IPO investor meeting, Anthropic's third-quarter revenue rose from $11.6 billion to $16.8 billion, achieving profitability on an adjusted basis. The company did not immediately respond publicly to the figures.
The Federal Reserve's Beige Book shows that price pressures are building. The latest survey indicates that the U.S. labor market remains in a state of 'low hiring and low layoffs,' with three Federal Reserve districts describing price growth as strong and another eight calling price increases moderate, including three noting that the pace of price increases is accelerating. Diesel, tariffs, and insurance costs were frequently cited by businesses as sources of pressure.
Two cargo ships sank near the Strait of Hormuz. Shipping and International Maritime Organization data showed that the Singapore-flagged container ship GFS Pride and the Antigua and Barbuda-flagged Cape Dao sank after being struck by projectiles. Prior to the war, roughly one-fifth of global oil and liquefied natural gas trade passed through the waterway.
Important Data and Events Preview
At 8:30 AM ET on October 15, the U.S. will release September PPI, core PPI, retail sales, initial jobless claims, as well as the October New York Fed and Philadelphia Fed manufacturing indices.
At 10:00 AM ET on October 15, the U.S. will release August business inventories data.
At 4:30 PM ET on October 15, Cleveland Fed President Beth Hammack will deliver a speech; at 11:30 PM, Fed Chair Kevin Warsh will deliver a speech.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


