
Memory Stocks Slide Again as Micron Drops Over 3%, But Goldman Says Market Overestimates CXMT Tech Impact
TradingKey - Oct 16: Memory stocks took another hit on Friday, with SK Hynix (SKHY) down over 5%, SanDisk (SNDK) down over 4%, and Micron (MU) down over 3%, bringing their weekly pullbacks to 18%, 15%, and 13%, respectively. The market fears that progress on the 4F2 architecture announced by ChangXin Memory Technologies (CXMT) could ease the memory chip shortage, thereby weighing on prices and manufacturer profits.
Behind this pullback lie two issues across different timeframes: whether immediate supply remains tight, and how big of an impact ChangXin's future capacity expansion will bring.
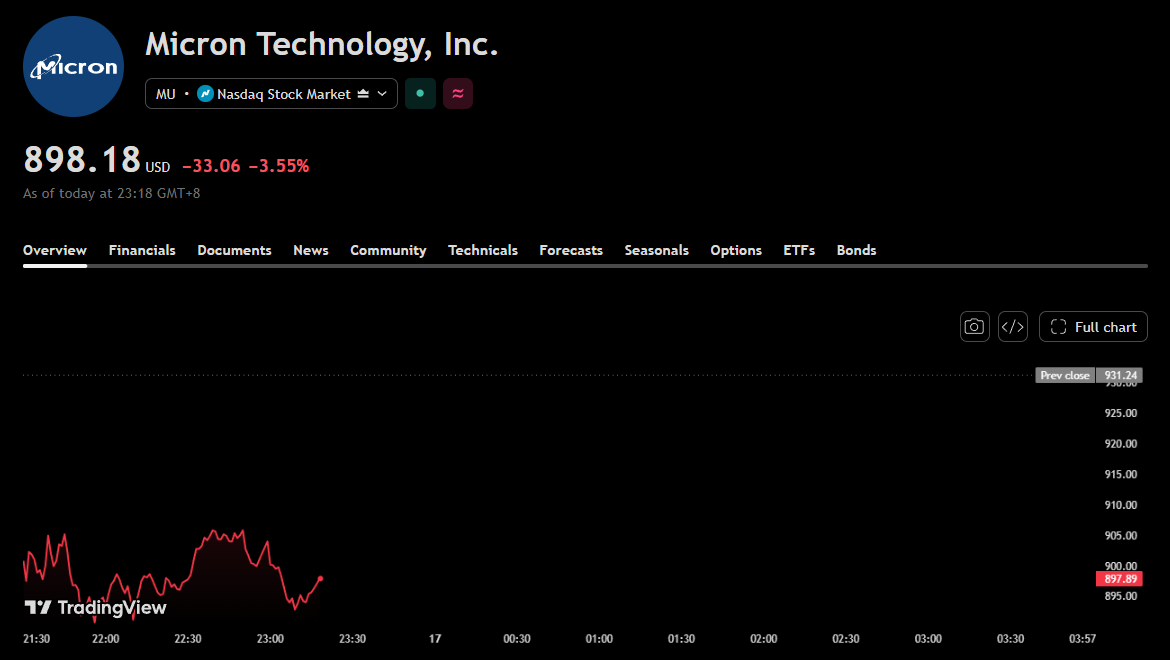
Micron Stock Chart, Source: TradingView
Current Supply Remains Tight as Data Center Demand Drives Up Price Hike Expectations
KeyBanc Capital Markets analyst John Vinh noted after field research in Asia that suppliers are shifting more memory capacity toward data centers. He projects that this will reduce memory supply for PCs and smartphones by 20% to 30% in 2027.
Based on AI demand and shifts in capacity allocation, Vinh projects that DRAM prices will rise 15% to 20% quarter-over-quarter in the fourth quarter of 2026, with NAND prices up about 20%; in the first quarter of 2027, HBM prices could surge 80% to 100% quarter-over-quarter. While these forecasts remain to be realized, they explain why the market remains focused on further upside in memory chip prices: data centers are absorbing more capacity, tightening available supply for other markets.
Customers are also locking in supply ahead of time. HP and Dell have extended their supply agreements through 2031, and Google is in talks for agreements covering through 2035. The growth in long-term agreements gives suppliers greater visibility into future demand.
ChangXin Expansion Is a Risk; HBM Catch-Up Still Faces Technical Barriers
CXMT's capacity growth cannot be ignored. Goldman Sachs forecasts that its monthly DRAM wafer capacity will increase from 290,000 wafers by the end of 2026 to 513,000 wafers by the end of 2028, an increase of about 77%. Goldman Sachs believes that market concerns over this additional supply are warranted.
However, Goldman Sachs also believes that the market has overestimated the technological impact of progress in 4F² architecture. CXMT still lags behind South Korean peers in advanced process DRAM and HBM; HBM competition depends not only on DRAM technology, but also on packaging and advanced base die manufacturing capabilities. Export controls restricting domestic Chinese foundries from acquiring EUV lithography machines further add to the difficulty of catching up.
Nor does capacity expansion mean being able to fully satisfy the domestic market. Goldman Sachs estimates that by 2028, CXMT will still only meet about 50% of China's domestic DRAM demand and 40% of its HBM demand. Consequently, Goldman Sachs believes that price-to-book ratios below 1x for Samsung Electronics and SK Hynix already reflect overly pessimistic expectations for a 2028 downcycle, making their risk-reward profile attractive.
Micron, SanDisk and SK Hynix Benefit in Different Segments
While the three companies face the same memory cycle, their areas of benefit differ.
Micron is aligned with the main demand drivers for DRAM and HBM. Vinh believes the survey results are most positive for Micron, as the number of its strategic customer agreements grew from 16 in the second quarter to 26 in the third quarter.
SanDisk is more directly tied to the NAND market. Beyond expectations of NAND price increases, the company has signed long-term agreements with eight customers, including several major tech companies.
SK Hynix's focus is on HBM demand and the long-term competitive risks posed by CXMT. The company has finalized long-term agreements with major customers. For SK Hynix, the immediate question to monitor is whether forecasted HBM price increases materialize; the longer-term variable is how quickly CXMT's capacity expansion translates into effective supply.
Therefore, CXMT's progress is worth tracking, but capacity expansion forecasts for 2028 should not be directly equated with an immediate reversal in supply and demand.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


