
Intel Plunges Over 27% Pre-Market, Stock Set for Biggest Single-Day Drop in 52 Years as PC Slump Shatters Recovery Expectations
TradingKey - Intel (INTC) shares are facing a new wave of sell-offs.
Following its third-quarter earnings report, Intel's stock price plummeted more than 23% in extended trading, with losses expanding to over 27% in Friday pre-market trading. If this decline persists through the regular trading close, Intel will post its largest single-day loss since 1974—a period of nearly 52 years—and could see more than $100 billion wiped from its market value.
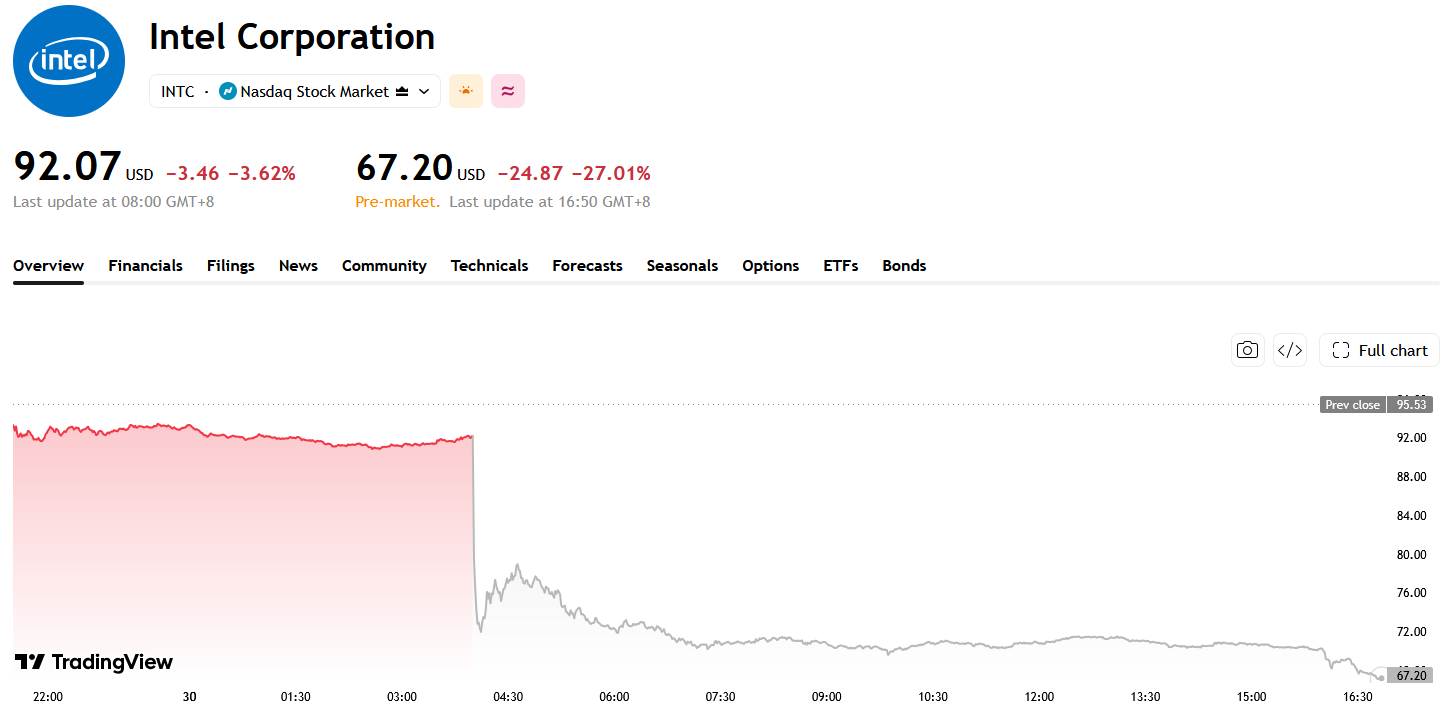
Source: TradingView
Intel reported third-quarter revenue of $16.5 billion, up 21% year-over-year, broadly matching market expectations; adjusted earnings per share came in at $0.52, also beating analysts' forecasts.
However, this growth failed to offset the pressure from its fourth-quarter outlook. Intel expects fourth-quarter revenue to range between $15.0 billion and $16.0 billion, well below Wall Street's average estimate of approximately $17.07 billion. Adjusted EPS is projected at $0.25, also falling short of the market consensus of $0.43. Based on the midpoint of the revenue guidance, Intel's top line in the next quarter could decline by around 6% from the third quarter, signaling weakening short-term operational momentum.
The pressure stems primarily from the traditional PC business. Third-quarter revenue from the Client Computing Group and Physical AI segment fell to $8.1 billion, down 5% year-over-year and 9% quarter-over-quarter. Memory chip shortages and rising prices pushed up system manufacturing costs, while corporate IT budgets remained squeezed, prompting PC makers to accelerate inventory reductions and pare back processor purchases. Management expects client business revenue to fall by more than 20% quarter-over-quarter in the fourth quarter, with PC market weakness potentially lasting at least through the first half of 2027.
Meanwhile, Intel failed to fully capitalize on growing demand for server processors. An explosion at its Kiryat Gat fab in Israel earlier this month halted production for about two weeks, which is expected to reduce fourth-quarter revenue by approximately $300 million and drag down gross margin by about two percentage points. The company estimates that revenue losses caused by the incident across two consecutive quarters could reach around $600 million, further constraining supply capacity for its Xeon server chips.
This leaves Intel squeezed on both fronts: PC processor demand is weakening, while server CPUs—despite outstripping supply—cannot be promptly converted into revenue due to the fab shutdown, advanced packaging substrate shortages, and manufacturing bottlenecks. Rapid growth in the data center business is therefore insufficient to fully offset the headwinds from the client downturn and production constraints.
Intel Foundry also remains in a high-investment phase. Despite notable revenue growth, the segment posted an operating loss of approximately $1.85 billion in the third quarter. Management expects 2027 to remain a key investment year, meaning the company may continue to face negative free cash flow pressure.
Intel's stock had previously surged on expectations around AI server demand, external financing, and manufacturing strategy improvements, more than doubling year-to-date. This reflected high market expectations for its turnaround prospects. Now, with fourth-quarter guidance exposing a triple threat of PC demand, supply chain, and cash flow pressures, investors are reassessing whether the prior stock rally ran ahead of fundamental improvements.
Meanwhile, several Wall Street firms quickly lowered Intel's price target. JPMorgan (JPM) trimmed its price target from $85 to $80; Piper Sandler (PIPR) reduced its target from $110 to $90; and Jefferies (JEF) sharply lowered its target from $120 to $85. The wave of downgrades reflects analysts' reassessment of how the PC downturn, production disruptions, and heavy manufacturing investments will weigh on Intel's earnings outlook, placing further short-term pressure on the stock.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


