



Applied Materials Q4 Earnings Preview: Revenue Expected to Grow 51%, Wall Street High Price Target at $900
TradingKey - Applied Materials (AMAT) will report its fourth-quarter and full-year fiscal 2026 financial results after the market close on November 12, Eastern Time, and host an earnings conference call at 16:30.
Applied Materials is a leading global semiconductor equipment manufacturer, primarily providing wafer fabrication equipment and related services to chipmakers. As of the close on November 11, the company's stock stood at $395.08, up 6.05% for the day.
In this earnings report, the market will focus on demand for DRAM, advanced logic chips, and advanced packaging equipment, as well as the company's outlook for the next quarter and fiscal 2027.
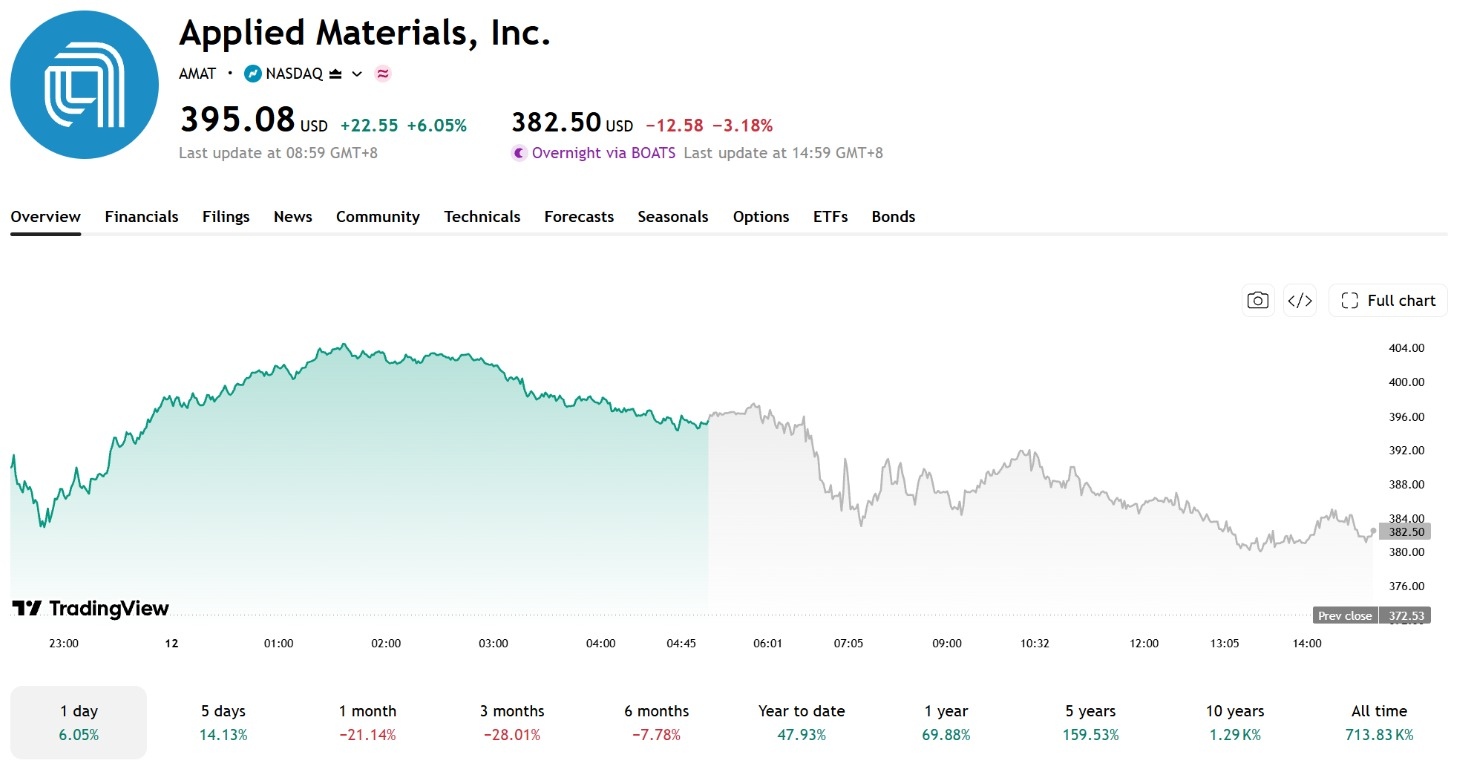
[Source: TradingView]
Market Expectations Slightly Above Company Guidance Midpoint as AI Device Demand Supports Growth
Analysts expect Applied Materials' fiscal fourth-quarter revenue to be approximately $10.3 billion, up about 51% from $6.8 billion in the year-ago period, and non-GAAP EPS of about $4.06, up approximately 87% year-over-year.
The company previously projected revenue of $10.25 billion, plus or minus $500 million, and non-GAAP EPS of $4.02, plus or minus $0.20. Both market expectations are slightly above the guidance midpoint, but remain within the company's projected range.
Looking back at the fiscal third quarter, Applied Materials reported revenue of $9.12 billion, up 25% year-over-year, and non-GAAP EPS of $3.50, up 41% year-over-year.
Specifically, Semiconductor Systems revenue was $7.04 billion, up 27% year-over-year, while DRAM revenue, including HBM packaging, rose 52% year-over-year. The company expects fiscal fourth-quarter Semiconductor Systems revenue of approximately $7.9 billion and a non-GAAP gross margin of approximately 50.4%.
Q4 Earnings Key Highlights: DRAM Deliveries and Next-Quarter Guidance
The ongoing buildout of AI infrastructure continues to drive demand for leading-edge logic, DRAM, and advanced packaging equipment. Applied Materials expects that in calendar year 2026, packaging revenue will grow by more than 70%, Applied Global Services (AGS) revenue will grow by more than 20%, and Process Diagnostics and Control revenue will grow by more than 50%. These are all full-year expectations rather than standalone guidance for the fourth fiscal quarter, and this earnings report warrants close attention to the actual revenue and equipment deliveries of the relevant businesses.
Management previously stated that several large customers have provided demand forecasts for the next eight quarters, helping the company plan its supply chain and capacity in advance. However, demand forecasts do not equate to firm orders. If component supplies or capacity constraints hinder deliveries, market demand may not necessarily translate into revenue in a timely manner.
Guidance for the next quarter is also worth watching. Applied Materials' first quarter of fiscal 2027 spans 14 weeks, one week longer than a normal quarter. When analyzing quarter-over-quarter revenue changes, this calendar factor must be considered to avoid attributing all the growth from the extra week to improving demand.
Demand for AI equipment provides Applied Materials with a solid growth foundation, but short-term results still hinge on order deliveries and revenue recognition. Investors should focus on the actual growth of the DRAM and advanced packaging businesses, as well as whether guidance for the first quarter of fiscal 2027 can sustain the growth momentum.
Wall Street's Highest Price Target Seen at $900
According to data from 41 analysts compiled by StockAnalysis, the 12-month average price target for Applied Materials is $620.78, implying a 57.13% upside from current levels, with a high price target of $900.
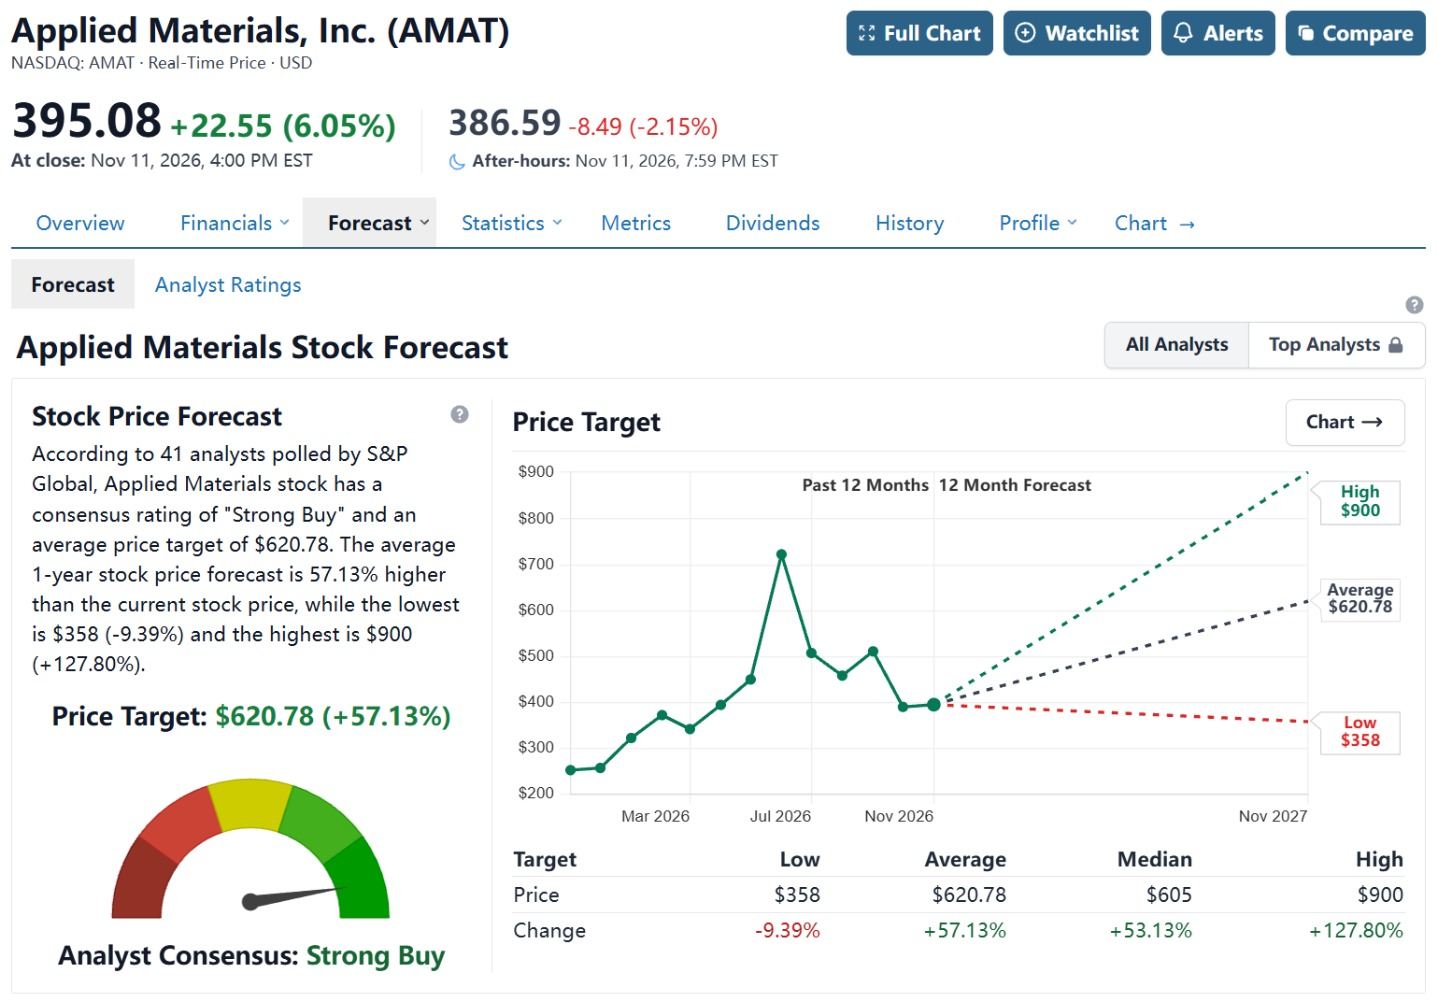
[Source: StockAnalysis]
UBS maintained its $695 price target and "Buy" rating, primarily bullish on growing demand for AI chips and believing that investments in DRAM, advanced logic, and advanced packaging equipment will continue to drive Applied Materials' results. Morgan Stanley (MS), meanwhile, took a cautious stance on valuation, arguing that the stock has largely priced in growth expectations with limited upside, maintaining a "Hold" rating and lowering its price target from $563 to $538.
In terms of earnings catalysts, if fiscal fourth-quarter revenue and earnings per share beat market expectations, and next-quarter guidance indicates that demand for DRAM, advanced logic, and advanced packaging equipment remains strong, the stock price is expected to find support.
Conversely, if results for the quarter meet expectations but forward guidance falls short of market expectations, or if equipment deliveries and gross margins come under pressure, investors may lower their fiscal 2027 growth expectations for the company.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


