



Cerebras Q3 Earnings Preview: OpenAI Compute Delivery and Margins in Focus as Wall Street's Highest Price Target Hits $325
TradingKey - Cerebras (CBRS) will report its third-quarter 2026 financial results after the market close on November 12, Eastern Time, and host a conference call at 5:00 p.m.
Cerebras is an AI chip company with wafer-scale processors and high-performance computing systems at its core, providing compute power for large model training and inference.
On November 12, as of press time, Cerebras shares were down 1.2% at $99.87 in premarket trading. The market is focused on whether the company can continue to expand its AI inference service revenue and the impact of data center expansion on profit margins.
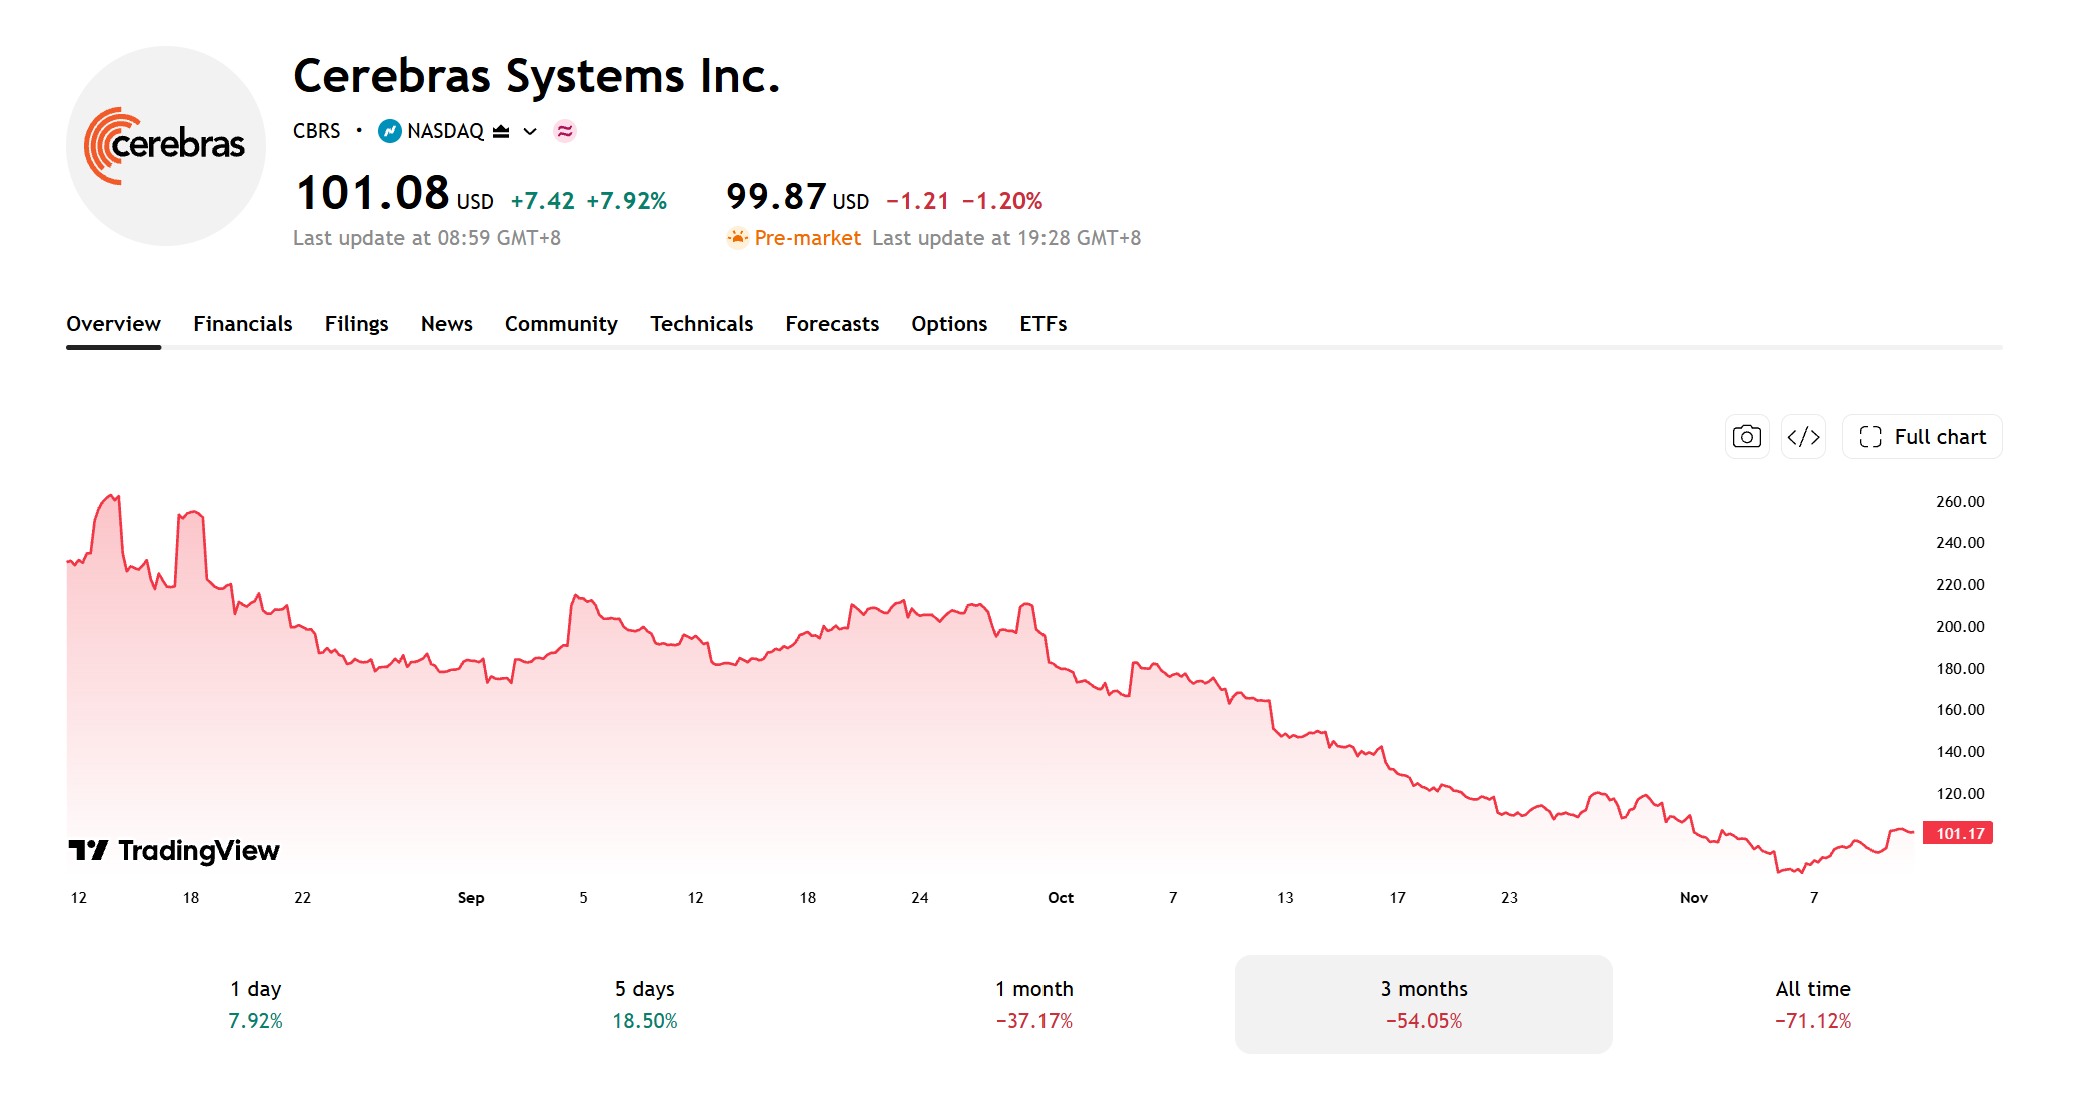
[Source: TradingView]
Market Expectations Near High End of Company Guidance
Cerebras expects third-quarter core revenue of $214 million to $216 million. Market consensus compiled by Zacks stands at $215.82 million, near the upper end of the company's guidance.
In the second quarter, Cerebras reported GAAP revenue of $180 million, up 74% year-over-year, and core revenue of $210 million, up 103% year-over-year.
Of that total, GAAP revenue from cloud and other services was $126 million, up 281% year-over-year. However, the company posted a GAAP net loss of $450.5 million for the quarter, continuing to face significant profitability pressure.
OpenAI Compute Delivery and Margin Performance in Focus for Q3 Earnings
In the second quarter, Cerebras' core gross margin was 40.6%, and its core operating margin was -16%. The company expects the two metrics to decline to 38%–40% and -25% to -23%, respectively, in the third quarter, with the core operating margin projected to deteriorate further.
CFO Bob Komin stated that the third quarter may be the trough for core gross margin, and margins are expected to improve in the fourth quarter as proprietary compute systems are brought online.
Delivery of OpenAI orders is another major highlight. OpenAI has committed to purchasing 750 megawatts of AI inference compute capacity. As of June 30, Cerebras' remaining performance obligations reached $25.4 billion, a substantial portion of which comes from the OpenAI contract.
Data center capacity that is already operational, under contract, and scheduled for delivery by the end of 2027 exceeds 600 megawatts, with subsequent revenue realization still dependent on the pace of compute deployment.
In terms of partnerships, the disaggregated inference solution co-developed with AMD is expected to enter production in the fourth quarter of 2026, while the collaboration project with AWS is scheduled to connect to Amazon Bedrock in the first quarter of 2027.
The company also raised its full-year 2026 core revenue guidance to $880 million to $890 million. Key points to watch on this call include whether full-year targets can be sustained and whether new capacity and partnership projects can be converted into revenue as planned.
Wall Street's Highest Price Target at $325
According to data compiled by StockAnalysis, 11 analysts have assigned Cerebras an average 12-month price target of $245.18, representing an upside of approximately 142.56% from its November 11 closing price of $101.08. The highest price target stands at $325 and the lowest at $170, with an overall rating of "Strong Buy."
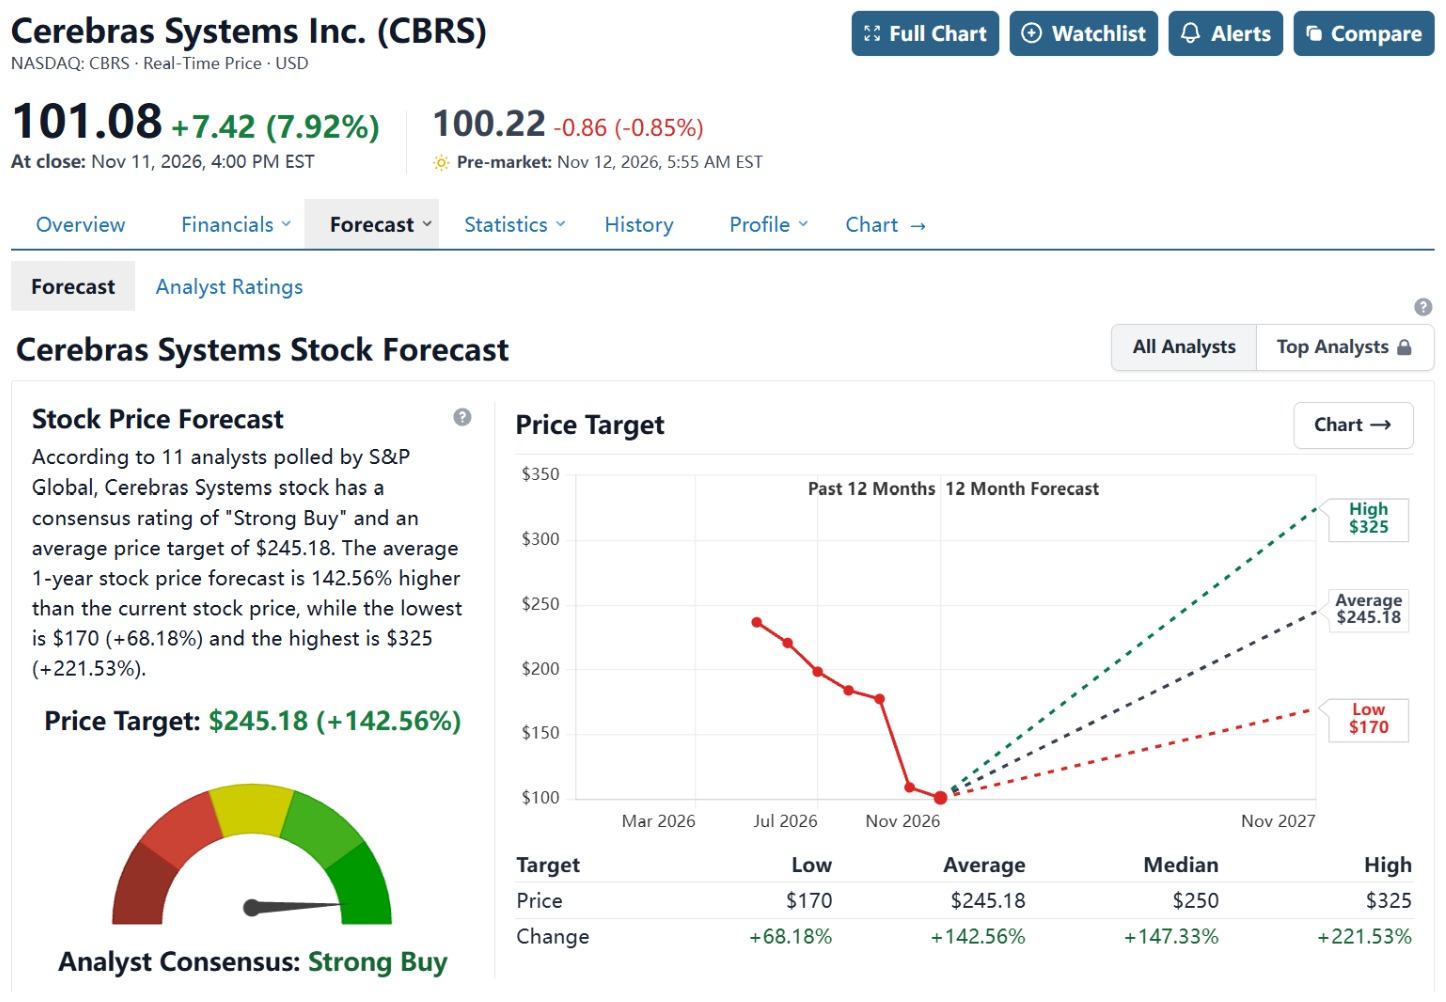
[Source: StockAnalysis]
Recently, Morgan Stanley, UBS, and Wedbush all lowered their price targets on Cerebras to $178, $250, and $190, respectively, while maintaining their bullish ratings.
UBS remains optimistic about growth opportunities driven by OpenAI orders, CS-4 chip shipments, and partnerships with AWS, Oracle, and others. Meanwhile, Wedbush views valuation compression across the semiconductor sector as the primary reason for lowering its price target, noting that some market concerns regarding wafer-scale chip lifespan, OpenAI orders, and AI inference demand are overblown, and projecting that the company's third-quarter results could beat expectations.
If core revenue meets guidance, gross margin remains within the 38% to 40% range, and the OpenAI project delivery timeline remains unchanged, the stock price could find support. Conversely, if margins fall short of guidance or data center deployment is delayed, the market may revise down expectations for future revenue growth.
Nothing in this material constitutes investment advice, personal recommendation, investment research, an offer, or a solicitation to buy or sell any financial instrument. The content has been prepared without consideration of your individual investment objectives, financial situation, or needs, and should not be treated as such.
Past performance is not a reliable indicator of future performance and/or results. Forward-looking scenarios or forecasts are not a guarantee of future performance. Actual results may differ materially from those anticipated.
Mitrade makes no representation or warranty as to the accuracy or completeness of the information provided and accepts no liability for any loss arising from reliance on such information.
Recommended Articles


